Paras Healthcare Limited
CLOSEDMainboard IPO · IPO Guide
IPO Market Value (GMP)
| LAST UPDATED | 23 Oct 2026, 09:57 |
|
PREMIUM / SHARE As per market view |
₹ 13 (1.88%) |
|
SUBJECT TO SAUDA Per allotted application |
Retail: 200 • S-HNI: 2,800 • B-HNI: 2,800 |
Lot Size Calculator (Rs 693/share)
| Application | Lots | Shares | Amount |
|---|---|---|---|
| 🏷️ Retail (Min) | 1 | 21 | ₹14,553 |
| 🏷️ Retail (Max) | 13 | 273 | ₹1,89,189 |
| 💼 S-HNI (Min) | 14 | 294 | ₹2,03,742 |
| 💼 S-HNI (Max) | 68 | 1,428 | ₹9,89,604 |
| 💼 B-HNI (Min) | 69 | 1,449 | ₹10,04,157 |
Final Subscription Breakdown
✅ Final Closed Figures · 23-Oct-2026 18:54As per financials, Paras Healthcare Limited has shown a top-line growth trajectory with total income rising at an 18.91% CAGR and net profit turning positive to Rs 43.83 Cr in FY26 and Rs 49.68 Cr in Q1FY27, RoNW is 12.98% (FY26) and the Post-Issue P/E is Negative (NM), Negative (NM), and 171.07 (79.31 TTM) respectively as per FY24, FY25, and FY26 earnings. So the issue looks aggressively priced. Also sudden price jump from ₹237 in April 2025 to ₹693 in October 2026 limits listing gains for short-term retail and HNI bidders. The company is a clinical specialty-led hospital platform providing tertiary and quaternary healthcare services in North India, Bihar, and Jharkhand offering products starting from basic outpatient consultations and diagnostic pathology tests to complex organ transplants, robotic surgeries, and high-acuity oncology treatments. So, we give a rating for this IPO. Readers must consult a qualified financial advisor prior to making any actual investment decisions.
Strong cluster presence across Tier-2/Tier-3 North & East India (Gurugram, Patna, Panchkula, Darbhanga, Udaipur, Ranchi, Srinagar, Kanpur) with an aggregate capacity of 2,211 beds.
High-acuity clusters (Cardiac, Oncology, Neuro, Gastro, Orthopedics, Renal) account for >72% of operational revenues, lifting ARPOB to ₹49,351 in Q1 FY27.
Operating EBITDA margins expanded from 10.54% in FY24 to 20.60% in FY26 and 22.33% in Q1 FY27 as newer hospitals in Srinagar and Kanpur reached operational break-even.
MD Dr. Dharminder Kumar Nagar brings 22+ years of clinical and administrative leadership, backed by institutional PE investors Creador, 360 ONE, and Axis AIF.
Asking FY26 P/E of 171.07x and 192% price jump over 18-month-old pre-IPO funding price (₹237) leaves negligible room for operational execution missteps.
DSO has lengthened to 76.28 days (DSO for Govt/PSUs stands at 166.69 days). Credit-impaired receivables stand at ₹416.63 Million.
Total contingent liabilities stand at ₹3,984.42 Million, primarily driven by corporate guarantees (₹376.4 Cr) and tax/statutory litigation (₹33.7 Cr+).
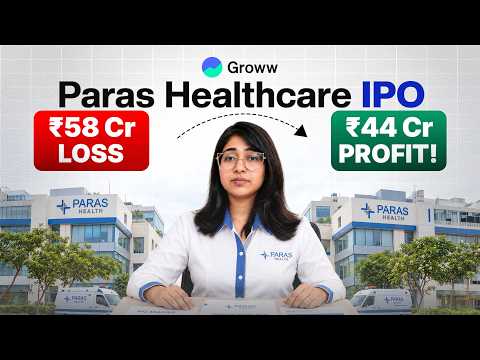
Company posted net losses in FY24 (-₹15.33 Cr) and FY25 (-₹57.98 Cr); long-term net margin consistency remains unproven over full business cycles.
Key operational facilities in Darbhanga, Panchkula, Ranchi, and Srinagar operate on unregistered lease deeds, creating potential legal or eviction vulnerabilities with lessors.
The sudden price jump from ₹237 in April 2025 to ₹693 in October 2026 limits listing gains for short-term retail and HNI bidders.
✅ Check Your Mainboard IPO Allotment Result
Direct link to registrar — query by PAN / Application No. / DP Client ID.
Related Videos & Analysis
Disclaimer
💬 Community Discussion
0 CommentsNo comments yet. Be the first to share your thoughts!
✍️ Post a Comment